

I’ll never forget the cold sweat I broke into when a letter from a debt collector arrived for an old cell phone bill I had completely forgotten back in 2014. It felt like a ghost had come back to haunt my bank account. The most confusing part? The ‘date of last activity’ on my credit report claimed the debt was only six months old. I knew that was a lie. I almost paid it just to make the anxiety go away, but that would have been the biggest mistake of my financial life. This sneaky tactic is called re-aging, and it’s a trap designed to keep you paying for mistakes that should have legally vanished years ago. Today, we are going to dive into exactly how to spot these zombie debts before they drain your savings or tank your progress.
Stop Paying for Debts That Legally Should Be Dead
The first time I tried to fix my own credit, I made a massive error: I called a collector to argue. That single phone call was a disaster. By acknowledging the debt without a plan, I accidentally gave them ammunition to keep reporting it. I didn’t realize that 5 things collectors do not want you to know about old debt include the fact that they often buy these accounts for pennies and then artificially refresh the dates to make them look recent. If you see an old account that suddenly has a recent ‘date of last activity,’ you are likely looking at a violation of your rights. You need to know how to prove a debt is too old to be reported before you even think about sending a check. According to the Federal Trade Commission, most negative information must be removed from your credit report after seven years, a rule specifically outlined in the Fair Credit Reporting Act. Collectors hate this rule. They want you to believe the clock restarts every time the debt is sold to a new agency. Spoiler alert: it doesn’t.
Is re-aging actually a thing or just a credit repair myth?
It is very real, and it’s more common than you think. Have you ever noticed an old debt suddenly looking brand new on your credit report? If so, you aren’t alone. I’ve seen neighbors and friends lose sleep over these ‘zombie’ accounts. The trick is to stop calling debt collectors and start mailing these forms instead. When you use a paper trail, you force them to provide the original delinquency date. My early mistake was assuming the credit bureaus would just ‘know’ the date was wrong. They don’t. They just report what the collectors tell them. You have to be the one to call foul. Learning how to use a debt validation letter to silence collectors is your first line of defense. We’re going to walk through the exact red flags you need to look for on your Experian or TransUnion files to ensure you aren’t being bullied into paying a debt that has technically expired.
Audit Your Report Like a Forensic Accountant
Think of your credit report like a crime scene. Most people just look at the ‘Balance’ column, but that is exactly where the debt collectors want your eyes to stay. To catch a re-aging scam, you have to look deeper into the metadata of the account, specifically the ‘Date of First Delinquency’ (DOFD). This is the day the clock started ticking, and legally, it never resets. If a collector buys your debt and puts their own ‘Open Date’ in that field to make it look brand new, they are effectively putting a fresh expiration sticker on a carton of sour milk. You need to learn how to read the data fields collectors use to track you because that is where the evidence of their tampering is buried. When I was cleaning up my own file, I found a medical bill from a 2015 ER visit that was suddenly reporting as ‘Opened’ in 2022. By focusing on the DOFD instead of the balance, I was able to prove the account was past its seven-year shelf life.
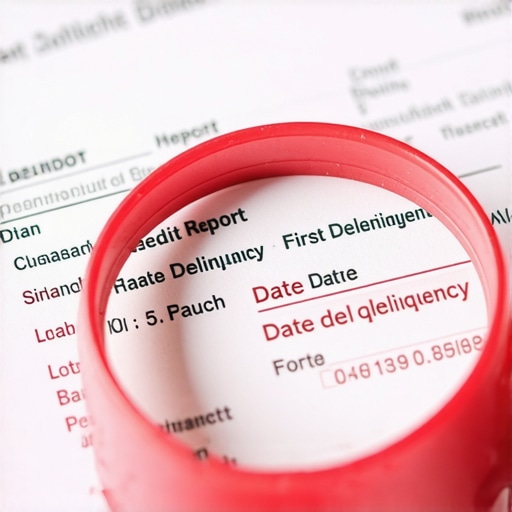
Find the Date of First Delinquency Before They Hide It
Your first move is to pull your ‘full’ credit disclosure. The free versions you get from apps often summarize the data, which is useless for this fight. You need the granular version that shows the month and year the account first went south. If you see that a debt has been sold three times and each time the ‘Date Opened’ gets more recent, you’ve found a violation. I once helped a friend who had a repossession from 2016 that was dragging down his score in 2024 because the newest collector reported it as a 2023 delinquency. We didn’t just ask them to fix it; we used how to fight a re-aged debt with one certified letter to point out the specific FCRA violation. This forces the bureau to look at the original creditor’s records rather than taking the collector’s word for it.
Use the Certified Mail Strategy That Actually Works
Stop using the ‘Dispute’ button on the credit bureau websites. Those portals are designed to process your request as a simple ‘not mine’ or ‘wrong amount’ claim, which the bureaus’ automated systems can verify in seconds. Instead, use the certified mail hack that forces bureau responses. When you send a physical letter, you can include ‘Exhibit A’—a screenshot or a previous report showing the true age of the debt. If you want to dispute errors like a pro, you must be surgical. Mention that you are aware of the ‘re-aging’ and that you will be filing a complaint with the Consumer Financial Protection Bureau if the illegally refreshed date isn’t corrected immediately.
Build a Paper Trail That Kills Collection Accounts
Evidence is your only currency here. If you have an old bank statement or a letter from the original creditor from five or six years ago, that is your smoking gun. Collectors count on you being disorganized. They assume you threw that 2017 utility bill in the trash. By maintaining the paper trail that kills collection accounts for good, you change the power dynamic. When I disputed that old medical bill, I attached a copy of my 2015 discharge papers. The bureau couldn’t argue with a hospital-stamped document. Within 14 days, the account was wiped clean. Remember, your goal isn’t to prove you don’t owe the money; it is to prove they no longer have the legal right to report it on your file.
Stop Trusting the Automated Bureau Portals
Most people believe that clicking the ‘dispute’ button on a credit bureau’s website triggers a deep, manual investigation into their financial history. This is the biggest myth in credit repair. In reality, your dispute is likely processed by e-OSCAR, an automated system that reduces your detailed complaint into a three-digit code. When you use these portals, you are essentially playing a game where the rules are rigged against you. This is the risks of using a bureau portal for complex disputes; the system isn’t designed to find the truth; it’s designed to confirm the data already in the collector’s database. A study by the Consumer Financial Protection Bureau (CFPB) highlighted that these automated processes often fail to include the actual evidence consumers provide, leading to a cycle of ‘frivolous’ labels and rejected claims. If you want results, you have to stop settling for verified and demand these specific records through physical mail.
Does paying off an old collection actually boost your score?
Contrarily to popular belief, paying off a zombie debt can sometimes cause your score to plummet. This is the ‘Oops’ factor that catches even savvy borrowers off guard. When you pay a collection account that has been sitting dormant for five years, the ‘Date of Last Activity’ updates to the current month. To the FICO algorithm, a five-year-old collection is less damaging than a brand-new one. By paying it, you’ve essentially told the scoring model that you have a ‘fresh’ delinquency. This explains why your score wont budge despite paying down debt. Before you send a dime, you must understand the difference between the credit reporting period and the statute of limitations for lawsuits. Have you ever fallen into this trap? Let me know in the comments.
The Hidden Danger of Acknowledging the Debt
There is a massive nuance that collectors use to manipulate you: the difference between a debt being ‘reportable’ and ‘collectible.’ A debt might be too old to appear on your credit report (7 years), but in some states, a collector can still sue you for it if the statute of limitations is longer. Conversely, making a single $5 ‘good faith’ payment can restart the clock on how long they have to sue you. This is why most people fail when challenging credit bureau errors—they accidentally reset their own legal liability while trying to fix a reporting error. You need to stop using the truth about those generic dispute letter templates that don’t address these legal nuances. If you don’t tailor your approach to your specific state laws and the Date of First Delinquency, you are just shouting into a digital void. You must be surgical with your evidence, or the bureaus will continue to rubber-stamp the collector’s lies as ‘verified.’Once you stop the bleeding caused by those automated portals, you need a system to ensure the zombies don’t just find a new way back onto your report. I spent years spinning my wheels because I was looking at the wrong data. If you want to dispute errors like a pro, you have to graduate from the free ‘Vantage’ scores offered by most banks and move to real-time FICO monitoring. I personally use myFICO because it gives me access to the exact versions lenders use for mortgages and auto loans. Knowing your key credit score factors every borrower must know is useless if you are looking at the wrong scoring model.
Ditch the Free Apps and Get Real Data
The biggest hurdle to long-term success is ‘Data Latency.’ Free apps often update once a week or once a month, but a collection can pop up overnight. By the time you see it on a free app, the damage is done. I recommend keeping a dedicated ‘Dispute Log’—a simple spreadsheet where you track every letter, Every Tracking Number, and every response date. This isn’t just for organization; it’s for legal ammunition. If a bureau fails to respond within 30 days, that log is your proof of their violation. It’s all part of the ultimate blueprint for effective credit repair.
The Secret Layer of Bureaus Most People Ignore
While you are fighting the ‘Big Three’ (Experian, Equifax, TransUnion), the debt collectors are often feeding data to secondary bureaus like LexisNexis and SageStream. These are the ‘back-office’ reports that lenders check when you apply for a house. If you don’t clean these up, a zombie debt can vanish from Equifax but still cause a loan denial because it’s lurking in your LexisNexis file. This is why you need to freeze your sagestream report today. Freezing these minor players cuts off the data flow that collectors use to verify their lies. According to a technical report by the National Consumer Law Center (NCLC), the e-OSCAR system often relies on these secondary sources to ‘validate’ debt without ever actually investigating the original documents. 
How can I keep my credit report clean for the next decade?
Maintaining a pristine file requires a ‘Defensive Credit’ mindset. I set up ‘identity monitoring’ alerts that ping my phone the second a new inquiry or account appears. I also suggest doing a ‘soft audit’ every six months by using the easiest way to track your fico score for free. The goal is to catch a mistake before it matures into a collection. If you see an address you don’t recognize or a misspelled name, fix it immediately. These small ‘metadata’ errors are often the hooks that collectors use to attach their debts to your file.
The Future of Borrowing is All About Trended Data
As we move deeper into the decade, the game is changing. Lenders are moving toward FICO 10T and VantageScore 4.0, which look at ‘trended data’—your behavior over the last 24 months, not just a snapshot of today. This means if you want to boost your credit score in 2025, you can’t just fix a mistake and go back to old habits. You need a consistent pattern of low utilization and on-time payments. I predict that AI-driven scoring will soon make it much harder to use ‘generic’ dispute methods, as algorithms will quickly flag non-human letter patterns. My advanced tip for you today: stop what you are doing and go freeze your secondary reports at LexisNexis and SageStream. It’s the single most effective way to prevent ‘re-aging’ from ever happening again.
Why Being Nice to Debt Collectors Always Backfires
Looking back at my own journey, the hardest lesson I learned was that silence and legal procedure are your only real allies. I used to think that being polite and explaining my situation would make collectors sympathize. I was wrong. Every “honest” explanation was just a piece of data they used to link me more tightly to the debt. I eventually realized that dispute errors aren’t just typos; they are legal opportunities to force the bureaus to follow the Fair Credit Reporting Act. Another lightbulb moment? Realizing that the credit bureaus are not government agencies. They are private, for-profit companies. When you stop treating them like authority figures and start treating them like data vendors, your strategy changes from “pleading” to “demanding accuracy.” Finally, I learned that a credit score is a game of rules, and if you don’t know the rules regarding re-aging, you are playing with a massive handicap.
The Essential Arsenal for Your Financial Comeback
I didn’t reach a high score by guessing. I used specific tools that cut through the noise and provided the leverage I needed. First, I stopped relying on free apps and started using myFICO to see the exact data lenders see. If you want to unlock your credit score potential, you need the real FICO 8 and FICO 9 scores. Second, the USPS Certified Mail receipt became my most valuable piece of paper; it is the only way to prove a bureau received your evidence within the legal timeframe. Third, I discovered that credit counseling isn’t just for people in over their heads; it is a source of credit counseling secrets that can help you navigate complex settlements without accidentally resetting those dangerous statute of limitation clocks.
Take the Keys Back from the Collectors
You are not defined by a mistake you made years ago, and you certainly shouldn’t be punished for a debt that should have legally expired. By learning how to dispute errors on your credit report and improve score, you are reclaiming your seat at the financial table. It takes persistence, and it takes a bit of a “forensic” mindset, but the payoff—a home, a new car, or just the peace of mind of a clean report—is worth every stamp and every letter. Start by following the ultimate blueprint for effective credit repair and don’t let up until every single zombie account is gone for good. Have you ever seen a debt suddenly reappear with a new date after you ignored it for years? Let me know in the comments below!